Britain will make debt relief for developing economies a central priority of its 2027 Group of 20 presidency, calling for faster restructurings, longer repayment periods and new rules to prevent small groups of creditors from blocking broad agreements.
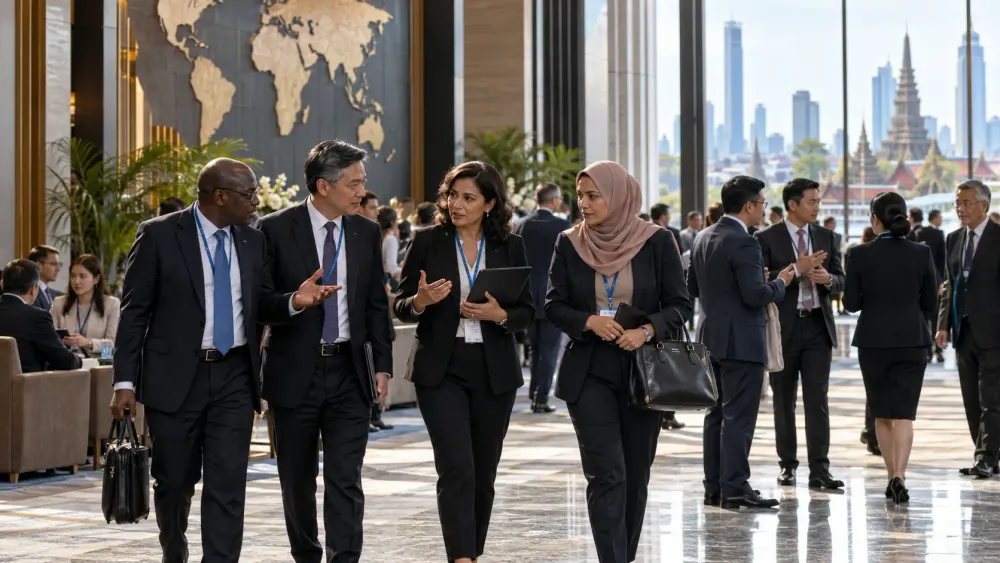
Foreign Secretary Ed Miliband set out the agenda Wednesday at the International Monetary Fund and World Bank annual meetings in Bangkok. In a formal speech, he argued that heavily indebted countries are losing fiscal room for public investment just as climate, energy and security shocks are becoming more frequent. The proposal is not a negotiated G20 settlement, but it puts the United Kingdom on record for using next year’s chairmanship to press creditors and multilateral lenders toward changes.
The immediate goal is to shorten the years-long process through which countries seek debt relief from governments, private bondholders and other lenders. Britain also wants repayment extensions and cheaper refinancing where those measures can restore sustainability without forcing deep cuts to essential services. Miliband said individual bondholders should not be able to hold out against a restructuring accepted by most creditors.
Reuters reported that Britain intends to carry those priorities into its G20 presidency, reviving an issue that has repeatedly frustrated borrower governments and international institutions. The G20 can coordinate major economies, but it cannot itself rewrite every loan contract or compel all private creditors to accept losses. Results would require cooperation from debtor countries, Paris Club lenders, China, bondholders, the IMF, the World Bank and regional development banks.
The debt squeeze behind the proposal
The World Bank’s latest debt data show why the issue has returned to the top of the development agenda. Developing countries paid $741 billion more in principal and interest on external debt than they received in new financing from 2022 through 2024, the largest such gap in at least half a century. That outflow does not mean every borrower is insolvent, but it shows how debt service can pull resources away from investment when new capital becomes expensive or scarce.
The IMF has separately warned that debt-service costs in vulnerable countries have climbed sharply as global interest rates rose. At the Bangkok meetings, Managing Director Kristalina Georgieva said average servicing costs had increased to about 14 percent of government revenue from 6 percent a decade earlier, according to independent reporting. Countries with narrow tax bases face especially difficult choices between paying creditors, maintaining public services and responding to emergencies.
Debt relief is also technically and politically complicated. Some governments owe money to a mix of multilateral institutions, other states, commercial banks and dispersed bondholders, each governed by different legal and policy constraints. Creditors worry that overly generous relief could weaken repayment discipline, while borrowers argue that delays deepen recessions and ultimately reduce recoveries for everyone.
The IMF and World Bank use a joint framework to assess whether low-income countries can meet obligations under plausible economic scenarios. Those analyses inform lending and grant decisions, but they do not automatically produce a restructuring. Negotiations still depend on creditor coordination, accurate disclosure of liabilities and agreement over how losses should be shared.
Beyond restructuring
Britain’s proposal combines debt reform with efforts to draw more private capital into emerging markets. Miliband called for multilateral development banks and bilateral finance institutions to absorb more risk and build a stronger pipeline of investable projects. He also advocated shifting more money toward disaster preparedness rather than waiting to finance recovery after climate or security shocks.
That approach reflects a recurring dilemma. Guarantees and blended finance can make infrastructure projects more attractive to institutional investors, but they do not erase currency risk, political uncertainty or weak project preparation. Public lenders must also guard against using scarce concessional funds mainly to repay existing private creditors rather than support new development.
The Center for Global Development welcomed the renewed attention to debt while warning that multilateral money intended for investment should not simply flow through borrowing countries to major creditors. That caution matters because fresh IMF or World Bank financing can stabilize a crisis, but without coordinated relief it may add another layer of obligations rather than create durable fiscal space.
A credibility test for Britain
Britain’s advocacy will be judged alongside its own development budget. The country reduced overseas aid from 0.7 percent of national income to 0.5 percent in 2021, and the government plans a further reduction to 0.3 percent in 2027 to fund higher defense spending. The Guardian noted that tension as Miliband made his case in Bangkok.
Supporters say structural reform can multiply the impact of limited public money by reducing delays and mobilizing private investment. Critics counter that rules changes cannot fully substitute for grants and low-cost lending, especially in fragile states and countries facing repeated climate disasters.
The next test is whether Britain can turn a broad call into specific G20 commitments: measurable deadlines for restructurings, stronger disclosure by borrowers and creditors, enforceable majority-voting provisions in bonds, and financing that does not simply recycle public funds into old debts. Until those details are negotiated, the Bangkok announcement is an agenda rather than a solution—but it places developing-country debt near the center of next year’s global economic diplomacy.