U.S. private-sector business activity accelerated in September to its fastest pace since July 2021, but the same survey showed cost pressures and supply delays intensifying sharply as companies struggled to keep up with demand.
The flash survey from S&P Global put its U.S. Composite Purchasing Managers’ Index at 58.4, up from 56.0 in August. Readings above 50 signal expansion. The result is an early but unusually strong indication that growth accelerated across both services and manufacturing near the end of the third quarter.
The strength was not cost-free. S&P’s input-price index jumped to 66.4 from 59.9, its highest level since October 2022, while delivery delays became the most widespread since July 2022. Those figures point to a business cycle in which orders are rising faster than some companies can add workers, secure materials or expand capacity.
A broad acceleration, not a single-sector spike
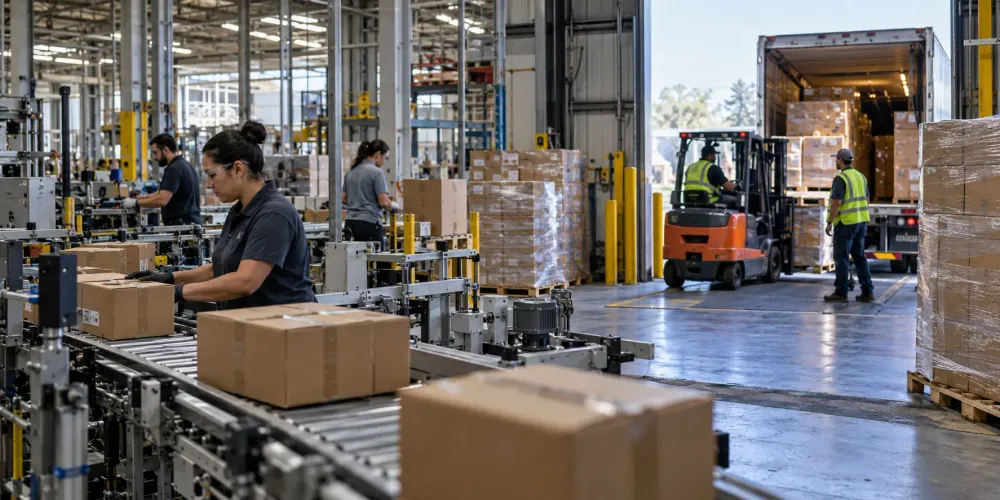
The improvement extended across the economy. The services PMI rose to 58.7 from 56.5, while the manufacturing PMI climbed to 57.0 from 53.9, according to figures independently reported by Reuters and Kitco. The manufacturing output component reached 56.7, reinforcing the signal that the acceleration was not confined to consumer services.
New orders rose even faster. The composite new-business index increased to 58.2 from 55.2, its highest level since March 2022. Firms also reported the largest buildup of unfinished work since May 2022, suggesting that incoming demand was outrunning current production capacity. Trading Economics likewise reported stronger orders, backlogs and employment across the September survey.
S&P said the survey’s relationship with official data was consistent with roughly 5% annualized economic growth in September and about 4% growth for the third quarter. That is a model-based comparison, not an official gross domestic product estimate. The flash PMI is assembled from business surveys and can move before harder measures such as production, retail sales and GDP, but it does not measure output directly.
That distinction is important for interpreting a single monthly release. A diffusion index records how many respondents report improvement or deterioration, not the dollar value of what they produced. The unusually high reading shows that expansion was widespread and rapid by recent standards, but subsequent government data could revise the apparent pace or reveal different conditions across industries.
Capacity strains turn growth into an inflation risk
The survey’s most consequential warning came from costs. Input prices rose at the quickest rate in nearly four years, and businesses increased their own selling prices at the fastest pace since May. Manufacturers reported especially severe increases, while service providers also faced higher labor and operating costs.
Supply chains were part of the problem. Vendor performance deteriorated at a pace rarely seen outside the pandemic period, Reuters reported, and firms cited material shortages, transportation disruption and longer delivery times. When suppliers cannot meet rising orders, companies often pay premiums for scarce inputs or faster delivery, then decide how much of that expense to absorb and how much to pass to customers.
The combination matters more than either signal alone. Strong orders ordinarily encourage investment and hiring. But when backlogs, shortages and input costs climb together, the expansion can produce inflationary pressure before new capacity comes online. The September survey therefore depicts both healthy demand and an economy encountering near-term limits.
Hiring improves, but labor supply stays tight
Businesses responded by adding staff at the fastest pace in more than four years. That hiring acceleration is consistent with a broad rise in new work, and it counters fears that recent interest-rate increases would quickly tip private employers into retrenchment. FXStreet separately confirmed the gains in both service activity and manufacturing.
Yet companies also told surveyors that finding suitable workers remained difficult. Labor constraints can reinforce backlogs and wage pressure even as headline employment grows. For managers, the practical question is whether stronger sales justify permanent hiring and capital spending or whether the September burst reflects demand that could cool as borrowing costs work through the economy.
Why the data complicate the Fed and business outlook
The report arrived one week after the Federal Reserve raised its benchmark rate by a quarter percentage point to a 3.75%–4.00% range. In its policy statement, the central bank described economic activity as solid and capital investment as robust, while warning that inflation remained elevated. The decision was unanimous.
Boston Fed President Susan Collins later said she supported the increase because inflation was still notably above the central bank’s 2% goal, according to another Reuters report. September’s PMI does not settle the rate outlook, but faster activity combined with stronger price pressure gives policymakers less room to treat inflation as a problem already contained.
For businesses, the immediate picture is similarly mixed. Sales pipelines look stronger, manufacturers are participating in the expansion and hiring has improved. At the same time, purchasing managers face rising input bills, delayed supplies and growing unfinished work. The next hard data will show whether firms can turn that demand into sustained production without another durable rise in consumer prices.