Alabama has opened a three-year utility-tax exemption for four energy-intensive agricultural uses, giving qualifying operators a new way to reduce electricity or natural-gas bills through Aug. 31, 2029.
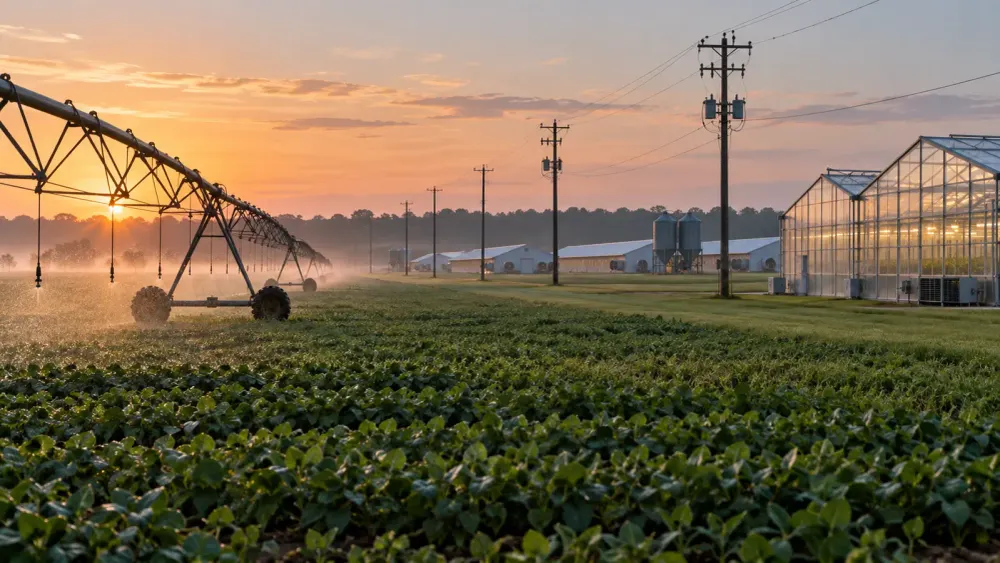
The Alabama Department of Revenue said in a notice posted Sept. 24 that the exemption applies to energy used in commercial aquaculture aeration systems, commercial greenhouses, pivot irrigation systems and poultry houses. It took effect Sept. 1 under Act 2026-595 and covers the state Utility Gross Receipts Tax associated with qualifying service.
The relief is not automatic. A business must obtain a Form STE-3 Utility Tax Certificate of Exemption from the department, then provide that certificate to its electric or natural-gas utility. The department's notice links both a paper application and an electronic path through My Alabama Taxes.
Businesses with mixed-use accounts face an additional practical requirement: separate metering. Revenue says that when a single utility account serves both exempt and nonexempt activity, only the qualifying use can be excluded, and the uses must be metered separately. That detail may require some farms to compare the expected tax savings with the cost of installing or reconfiguring meters before applying.
The exemption is also narrower than a general agricultural energy break. The department says it does not cover electricity or gas used to produce industrial hemp or cannabis. The same limits appear in the state-code provision implementing the act, which sets the Sept. 1, 2026, start and Aug. 31, 2029, expiration.
Alabama's utility gross-receipts system taxes utilities based on their receipts from customers. The Revenue Department's pending update to Rule 810-6-5-.26 lists the underlying monthly tax brackets for electricity, natural gas and domestic water: 4% on receipts up to $40,000, then graduated amounts above that threshold. The exemption removes qualifying farm energy from the taxable measure rather than creating a rebate after the fact.
The rule amendment also shows how implementation is still moving through the administrative process. Revenue says the change incorporates Act 2026-595 and removes older language about joint refund petitions. Its rulemaking tracker places the amendment in “pending final adoption” status after an Aug. 4 hearing, meaning it is awaiting the state's required legislative-oversight period.
The filing says the proposed rule itself does not increase the cost of goods or services and does not carry an agency-identified economic impact. That assessment addresses the rule amendment, not the value of the tax break to individual farms. Revenue's public materials do not quantify how many accounts may qualify or how much revenue the state expects to forgo during the three-year window.
For eligible operators, the immediate step is administrative rather than legislative: document the qualifying equipment, confirm that utility service is separately metered where necessary, and secure the STE-3 certificate before expecting the exemption on future bills. The department has not published an estimate of statewide savings, so the benefit will depend on each operation's energy consumption and billing profile.